1st Securities Mortgage
Call or text734.888.6728
See if I qualify
Funds open now in Westland, Taylor, Detroit and Pontiac

Your city will put up to $25,000 toward your first home.

Participating Michigan cities set aside federal housing dollars for first-time buyers. It goes toward your down payment, closing costs and prepaids, and after five years in the home it's forgiven. Most buyers have never heard of it. Most lenders have never used it.

  • 60-second check, no credit pull
  • Sean reviews your credit and income before you shop
  • Verified with the program on Nov 4, 2026
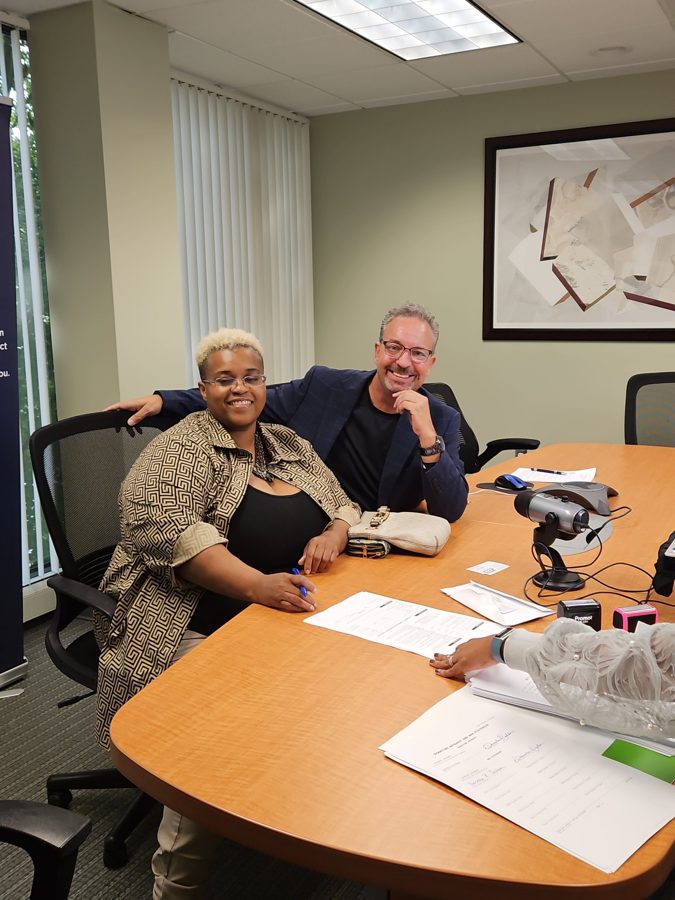
A couple at their closing with Sean Cragg
Closing day, Downriver

Not a first-time buyer, or buying somewhere else? There are other options.

See if you qualify

About 60 seconds · no credit pull

Checking does not affect your credit. Your information stays with our team.

Where the money is, city by city

Each city sets its own amount and runs out on its own schedule. When it's gone, it's gone until it's replenished, and nobody gets a date in advance. The buyers who are ready when it comes back are the ones who get it.

✓Amounts, caps and terms confirmed in writing with the program administrator on November 4, 2026. Funding changes without notice; we check again before every pre-approval.

Ten minutes that explain the whole thing

City assistance and lender assistance are not the same thing. Press play to hear how they differ, what each one covers, and which one may fit your situation. Listen while you drive.

The voice in this recording may be AI-generated. General information only, not an offer of credit or a pre-approval.

City DPA vs. lender DPA
Homebuyer briefing · under 10 minutes

Two underwriters look at your file. They don't always agree.

On a city-assisted purchase, the lender's underwriter and the program's underwriter each decide what your income is. The lower number decides what house you can afford. Finding that out the week of closing is the nightmare. Finding it out first is the whole job.

Your mortgage underwriter

FHA, conventional, VA or USDA. Fixed guidelines, no wiggle room.

  • Counts overtime, bonus and second-job income only with history
  • Applies the loan program's own debt-to-income limits
  • Needs a minimum credit score for the loan
The city program's underwriter

Its own method for counting household income, and its own ratio limits.

  • Counts income of everyone 18+ who will live in the home
  • Applies a housing ratio of 35% (40% in Westland) and, in most cities, a 43% total debt ratio
  • Sets no minimum credit score; your first mortgage still has to be approved
Sean runs both sets of numbers before you shop.If anything looks questionable, he gets your effective income agreed with the program in writing before he issues a pre-approval, because that number decides your price range.
Run my numbers

30 years of answers to questions nobody asks

Rates and costs are what everyone asks about. These are the things that actually trip people up between pre-approval and keys. Tap a question and Sean answers it.

In Sean's voice. The audio is AI-generated from Sean's own voice and his own words, reviewed by him before it was posted.

8questions · about 8 minutes total
  1. The answer is in your purchase agreement, not your closing date. Discuss possession with your realtor before you sign, so you both have a clear understanding. Sometimes you get the keys at closing. Sometimes the seller stays thirty or sixty days after closing, and sometimes they pay you for that time.

    My recommendation is not to give notice on your apartment until we're through underwriting and have a better picture. Things can come up on a mortgage that are unexpected and outside your control. That's my opinion, based on years of experience.

  2. The appraiser confirms that the sale price is supported by the home's value. That protects you and the lender, since the property is the collateral for the loan.

    The appraiser also does a health and safety check on the property. Examples include peeling paint, missing handrails, trip hazards, broken or pitted concrete, and smoke detectors. If the appraiser finds an item that needs repair, you and your agent negotiate who pays for it. Walk the property with these in mind before the appraisal, so the obvious repairs are done ahead of time.

    The attic and crawl space also have to be inspected. If the appraiser can't safely reach them, the appraisal isn't complete. Those areas are then subject to a re-inspection, and the appraiser charges a re-inspection fee. Clear any access points before the appraiser visits, such as an appliance blocking an entry.

    Who pays that re-inspection fee? Often it's the buyer, when the property wasn't ready for the appraiser. Talk to your agent about that up front, so you don't pay for an avoidable re-inspection.

  3. They can, and it can change your payment in a meaningful way. In Michigan, the taxable value is reset after a sale. The new value generally takes effect for the tax year after the sale, so the increase often shows up on a bill several months to about a year after closing. The exact timing depends on your closing date.

    First, file the Property Transfer Affidavit within 45 days of closing. Your title company or agent can help with that.

    Second, I strongly suggest that before you sign the purchase agreement, if you really like a property, take a minute and call the city assessor's office with the address. Ask what the taxes are today, what they may be after reassessment, and when the new amount will start appearing on the bill. Planning for that one call can keep your monthly payment from surprising you.

    If you think the reassessed value is wrong, you can appeal it. Each city has a Board of Review, which meets once a year in March. Bring a copy of your appraisal and compare the square footage, room count, and year built with what the city has on record, since those details don't always match. Your realtor is usually capable and willing to help with this process. We're also available as a backup, or to help with anything you need along the way.

  4. An estate sale isn't a problem by itself. The problem is when the property is held up in probate, because that can take a long time, and it's important to know that up front.

    Ask the right questions before you sign. Is the property in probate? If so, has the court approved the sale yet? If not, how long does that process normally take?

    Here's why it matters. You may think you're closing in 30 days, and you might. But you might also close in 130 days, waiting on the court. Know before you sign the purchase agreement, so you're not stuck in a contract you can't plan around.

  5. Buying with a partner, a friend, or a sibling can work really well. Life changes, though, and sometimes two people who bought a home together find themselves in a situation where one wants out. Nobody likes to plan for that, but planning for it is what keeps everyone treated fairly.

    A common question is, "If I sign the deed over to the other person, am I free of the mortgage?" The answer is no. Signing the house over doesn't take you off the loan. You still owe the debt.

    That's why I recommend putting a short written agreement in place before closing. It should cover who pays what, and what happens if one of you wants to sell or move out. As the saying goes, good fences make good neighbors. A clear agreement means everyone knows where they stand.

    I also recommend talking to an attorney about your situation. They can help you put that agreement in writing and make sure it protects you both.

  6. I hear this every time a buyer transfers to me. They were pre-approved somewhere else a week ago, and they ask me not to pull their credit because they're afraid it'll drop. It's usually a misunderstanding.

    I can't tell you anything real about your file without looking at it. That's not me being difficult; it's the job. And the fear is mostly a myth. Mortgage credit checks made within a shopping window are generally counted as one inquiry, so my pull doesn't stack on top of the other lender's. A single inquiry typically has a small effect anyway.

    If your score moved since their pull, it's usually because a card reported a new balance or an account got a month older, not because of the inquiry. Credit moves a little every day, with or without me.

    So let me look. If the other lender's numbers are good, I'll tell you to stay put. If they're not, you want to know now, while there's time to fix it.

  7. Your pre-approval is based on your finances as they looked when we applied: your income, your debts, and your credit. The underwriter will check all of it again right before closing. Changes aren't the end of the world, but a change I don't know about can turn into a problem the week of closing, when there's the least time to fix it.

    So between now and closing, a few things to keep in mind.

    One: if you're thinking about changing jobs, hours, or pay, even for a better job, call me first. I'll tell you whether it matters and how to handle it.

    Two: hold off on new credit. No new car, no store card, no co-signing for a relative. A new payment can push your debt ratio over the line.

    Three: don't move money around without telling me. No large or cash deposits, no transfers between accounts I haven't seen. Every dollar that goes toward your purchase needs a paper trail.

    Four: tell me everything, early. An old job, a tax issue, a gift from family. Almost everything is fixable early and a headache late.

    Life happens, and most things can be worked through. Just call me before you make the change, not after.

  8. Buying with city down payment assistance means two approvals. Your mortgage has its own underwriting process and guidelines that must be met. The city's assistance has a separate review with its own guidelines that must also be met. Debt-to-income ratios are one of the differences between them.

    The two don't calculate income the same way. That's why it's so important to get your documentation to me well in advance. I can determine what counts as qualifiable income, meaning what the lender and the city will each allow you to use. Knowing that before you sign a purchase agreement means you know your price range before you fall in love with a house, and there are no surprises later.

    When you work with me on city assistance, you have one point of contact. I collect the documents for your mortgage and for what the assistance program needs, so you aren't getting separate requests from different people for the same paperwork. I handle the coordination between the parties, so you get one clear process and one person who knows where your file stands.

    If you'd like more detail on how this works, call me anytime.

    This is general information, not an offer of credit or a pre-approval. Program rules and funding change, and my team verifies everything at application.

Have a question that isn't here? Text it to 734-888-6728 and Sean's team will answer it. The good ones end up on this page.

See if you qualify

Why this isn't the "down payment help" you've seen advertised

Sean offers the lender-funded programs too, and they're the right answer for buyers outside these cities or who don't qualify. For buyers who do qualify, it's not close.

Lender-funded assistanceCity assistance
How muchAbout 3% of the price (3.5% FHA). On a $200,000 house, roughly $6,000 to $7,000.Up to $14,500 to $25,000, depending on the city.
What it coversDown payment only. Nothing toward closing costs, escrows, insurance or prepaid interest.Down payment, closing costs and prepaids.
Seller concessionsYou still ask the seller for thousands. Against another offer at the same price, yours looks weaker.Shrinks what you ask for, or removes it. Your offer stands on its own.
PaybackSometimes forgivable, sometimes a loan with its own monthly payment.0% and no monthly payment. Forgiven after 5 years in the home (3 in Detroit).
Credit scoreMinimum score required.No minimum on the program side.
Your own moneyVaries by program.At least $1,000. Earnest money and your inspection typically count toward it.

The $1,000 is the program's minimum, not necessarily your total. What you bring to closing depends on your file; for many buyers it lands near a security deposit and first month's rent.

How it works

Answer a few quick questionsThe home you want, your household, your finances, roughly. About a minute.
15-minute call with SeanHe runs both sets of numbers and tells you plainly where you stand and what the city could cover.
Class and pre-approvalTake the required homebuyer class. Sean settles anything questionable with the program before he issues your pre-approval.
Shop with the money lined upBoth approvals run at the same time. A prepared file can close in about 30 days.

Helping buyers use city money before most lenders knew it existed

Sean Cragg has spent 30 years in Michigan mortgage lending, about 25 of them walking first-time buyers through these city programs. He lends across the state, seven days a week, but Downriver is home turf: born in Taylor, 25 years there, still volunteering at a local food charity every week.
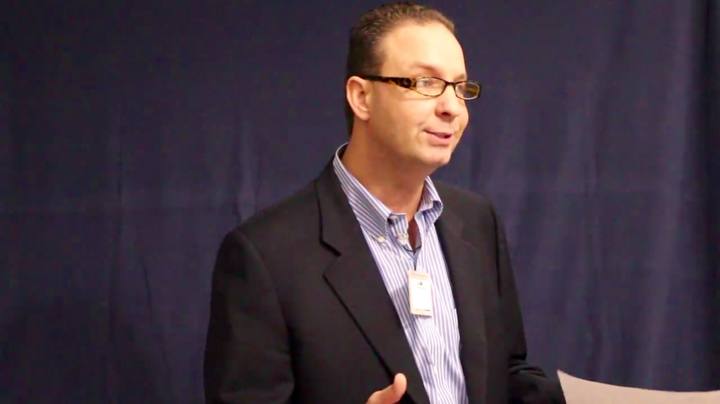
Sean presenting to a homebuyer class in the 1990sThe '90sTeaching homebuyer classes before the programs had websites. Yes, that's the hair.
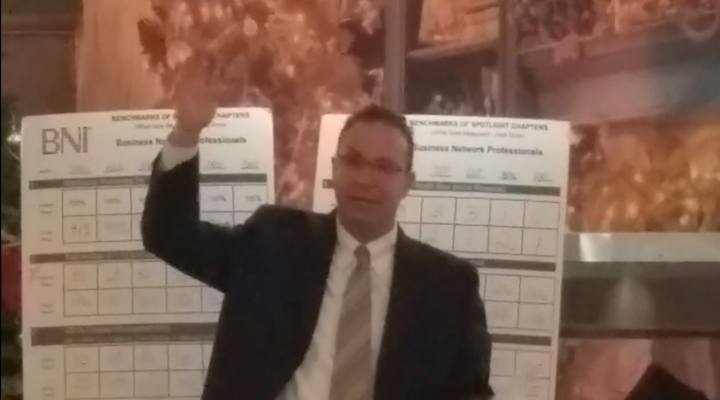
Sean presenting to a business groupCredit coachingTeaching buyers how to raise a score 100 points, on camera, 11 years ago.
Sean Cragg Team pageThe teamHis assistant and processors: 80+ years of combined lending experience.
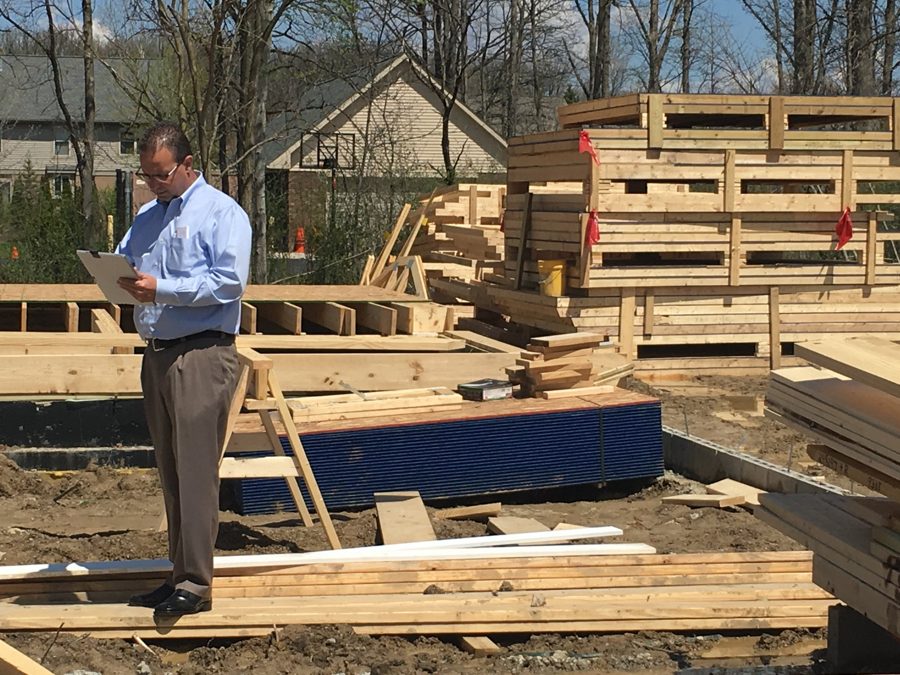
Sean at a construction siteEvery kind of houseKnows which houses pass a city inspection, and which won't.
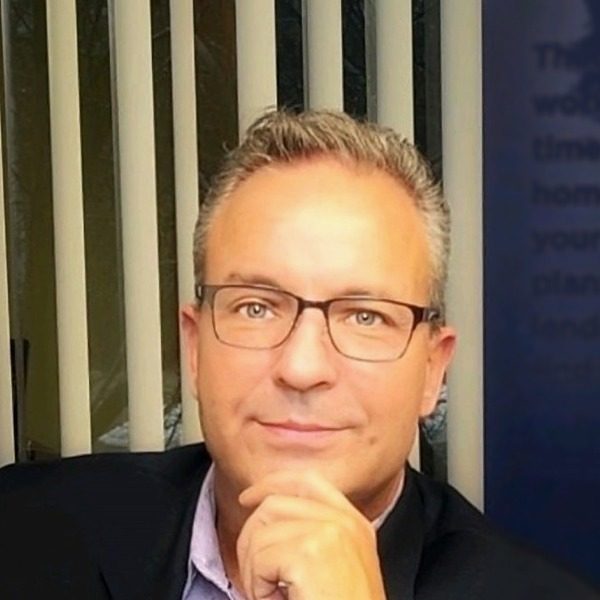
Sean Cragg todayTodayStill at the closing table with first-time buyers every week.
City programs, 25+ yearsWestland, Taylor, Detroit, Pontiac and the programs before them.
Argues for you firstQuestionable income gets settled with the program before the pre-approval, not the week of closing.
FHA, VA, USDA, conventionalWhatever fits, including zero-down options for veterans and rural buyers.
Seven days a weekWeekend coverage, so an offer never waits until Monday.

The agent matters more on these deals

A city-assisted purchase has an extra inspection and an extra underwriter. An agent who has done it knows what to look for before you write the offer. One who hasn't learns on your file. Here's what a DPA-ready agent does differently.

  • Has closed city-assisted purchases and tells the seller up front how the timeline runs
  • Walks the house for the obvious inspection failures before writing: peeling paint, missing handrails, a dead furnace
  • Gets the seller to fix those items in the contract, so the appraiser and the city inspector aren't sent back out at your expense
  • Writes the offer with the price cap and the assistance in mind so it isn't rejected on day one
  • Has Sean's team on speed dial for the thing that pops up, because something always does

Don't have an agent yet?

Sean will match you with an agent in your city who has closed these programs with him. No cost, no obligation; you choose whether to work with them.

Match me with an agent
Are you a real estate agent? Sean has buyers in these cities who need one. Join the DPA-ready agent roster.

Program rules, city by city

Confirmed with the program administrator on November 4, 2026. Income limits change each year; Sean's team checks the current figures at application.

Not ready yet? That's the best time to start.

The Homebuyer Survival Kit is a weekly text series: what to fix on your credit, what counts as income, how much cash you'll really need, and what to have ready the day a city's funds come back. One question a week, answered by Sean's team.

Text KIT
to 734.888.6728Send the text

Over the income limit, owned a home recently, or buying somewhere else?

You may still have help coming. Sean works with lender-funded assistance programs with higher income limits and no city requirement. Fill out the form anyway and he'll find what fits.

Check my options
Sean Cragg

Sean Cragg

Senior Loan Officer at 1st Securities Mortgage, Bingham Farms. Thousands of Michigan families have bought their first home with Sean. He'll tell you straight whether a city program fits you, and if it doesn't, what will.

NMLS #144411 · 1st Securities Mortgage NMLS #116848 · 30150 Telegraph Rd, Ste 320, Bingham Farms, MI 48025 · Call or text 734.888.6728
EQUAL
HOUSING
LENDER
Sean Cragg, NMLS #144411. 1st Securities Mortgage, NMLS #116848, 30150 Telegraph Rd, Ste 320, Bingham Farms, MI 48025. Equal Housing Lender. Licensed by the Michigan Department of Insurance and Financial Services. Down payment assistance is offered by the participating cities and is not a 1st Securities Mortgage product. Assistance is funded with federal housing dollars allocated to each city. Amounts, eligibility, income and asset limits, ratios, price caps and fund availability are set by each program and can change or close without notice; figures on this page were confirmed with the program administrator on November 4, 2026. Sean Cragg and 1st Securities Mortgage are not affiliated with, endorsed by, or acting on behalf of any city, county, or the agencies that administer these programs, and receive no compensation from them. 1st Securities Mortgage is compensated as the lender on your mortgage in the usual way; assistance funds may be applied toward closing costs, which can include lender fees. City assistance is a deferred second loan that must be repaid in whole or in part if the home is sold, refinanced or stops being the buyer's primary residence during the program period. A minimum buyer contribution of $1,000 applies; your total cash to close depends on your transaction. Renovation (203k) loans are not permitted with city assistance. Answers on this page give an early estimate only and are not a loan approval, pre-approval or commitment to lend. All loans are subject to credit approval and program guidelines. Audio and video on this page may use AI-generated voices and are for general information.